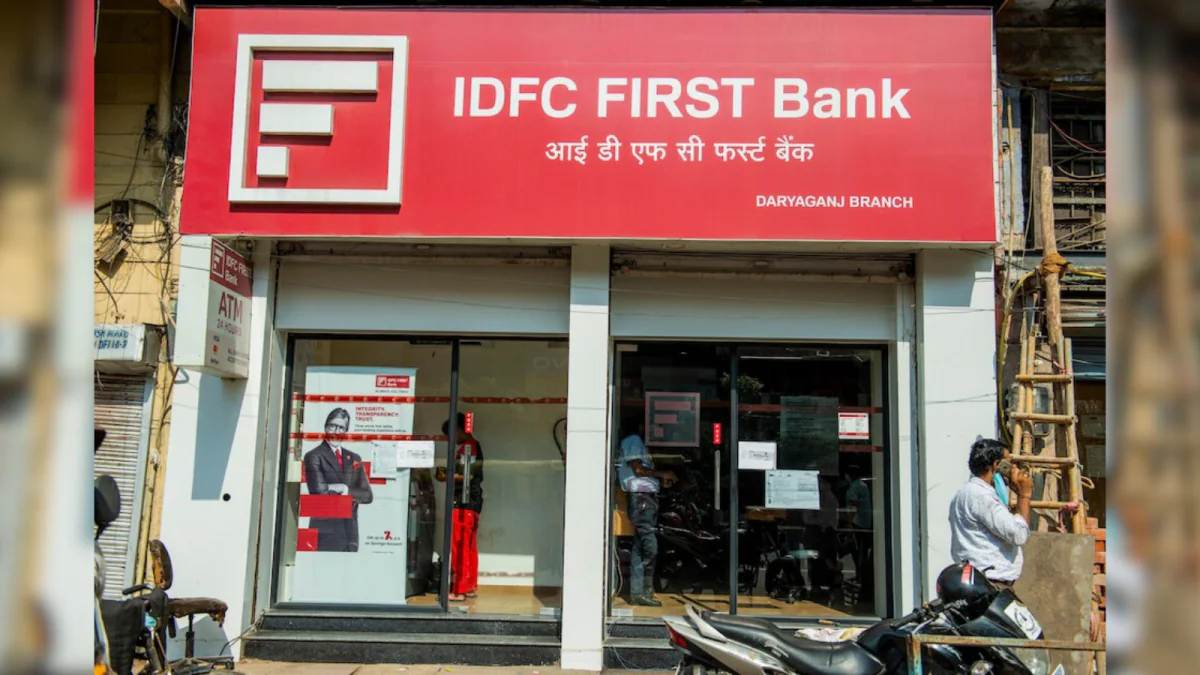
Mumbai: IDFC FIRST Bank reported a 196.5% year-on-year increase in profit after tax (PAT) to ₹1,045 crore for the second quarter of FY27, marking its second consecutive quarter with profits exceeding ₹1,000 crore. For the half year ended September 30, 2026, PAT stood at ₹2,120 crore, while return on assets (ROA) was 0.99%.
The bank recorded strong growth in deposits, which rose 25.9% year-on-year and 11.8% quarter-on-quarter to ₹3,48,583 crore. Its average current account and savings account (CASA) ratio stood at 48.4% during the quarter, compared with 50.1% previously. The bank attributed the decline primarily to the mobilisation of foreign currency non-resident (FCNR-B) deposits.
Loans and advances, including credit substitutes and FCNR(B)-backed loans, increased 30.1% year-on-year to ₹3,46,913 crore. Excluding loans secured by FCNR(B) deposits, growth stood at 22.2%, gross of inter-bank participation certificates (IBPC).
Core operating profit, excluding trading gains, grew 38.5% year-on-year to ₹2,527 crore. The bank also reported an improvement in its core cost-to-income ratio to 70.16% in Q2 FY27 from 70.73% in the preceding quarter. Operating expense growth remained around 500 basis points below income growth for the second consecutive quarter.
Asset quality remained stable, with gross non-performing assets at 1.32% and net non-performing assets at 0.40%. Credit cost, measured as a percentage of average assets, declined to 1.01%. The bank’s return on assets for the quarter was 0.93%.
During the quarter, IDFC FIRST Bank mobilised ₹34,390 crore, or approximately US$3.6 billion, in FCNR(B) deposits despite having no branch, subsidiary or representative office outside India. According to the bank, these deposits largely carry tenures of three to five years and provide long-term structural liquidity. Their fully loaded cost, including priority sector lending benefits, is approximately one percentage point lower than the cost of comparable domestic fixed deposits.
The bank said the mobilisation is expected to support net interest income, profit, earnings per share and return on equity, although it creates some optical pressure on net interest margin as the balance sheet expands.
Another milestone was the bank’s first international credit rating, with S&P Global Ratings assigning it an investment-grade long-term rating of ‘BBB-‘.
Commenting on the results, Managing Director and CEO V. Vaidyanathan said the bank had crossed the ₹1,000-crore quarterly profit mark for the second consecutive quarter. He highlighted improved operating leverage, a declining cost-to-income ratio and the benefits of long-tenure FCNR(B) deposits, expressing confidence in sustaining the bank’s performance momentum.
 https://www.youtube.com/watch?si=RtToJsBhYBatUrym&v=mOuYNSdhjHA&feature=youtu.be